Principal-led. Our principals have led 350+ commercial projects across the western United States.
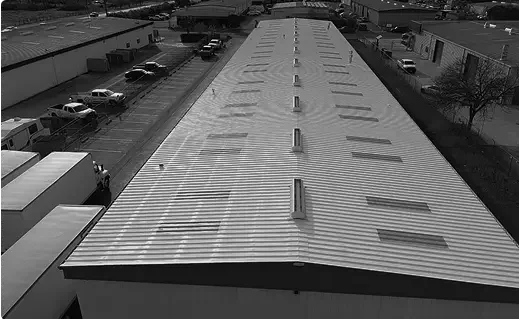
Most commercial owners evaluate roofing, solar, and HVAC projects based on project cost. Capstone works with specialized commercial lenders to structure equipment financing around the asset—not the real estate.
A UCC-1 financing structure uses the installed equipment as collateral rather than recording a mortgage position against the real estate.
The lender files a Uniform Commercial Code (UCC) financing statement against the financed equipment, creating a security interest in the infrastructure asset itself. For commercial owners, this distinction can significantly improve flexibility compared to traditional real-estate-collateralized financing.
Refinance Flexibility
Traditional real estate liens can complicate refinancing transactions.
Sale Flexibility
Potential buyers evaluate encumbrances carefully.
Portfolio Recapitalization
Institutional ownership groups frequently restructure capital stacks.
Acquisition Strategy
Preserving borrowing capacity against the real estate can create future opportunities for growth.
Project Underwriting
The lender evaluates ownership, financial performance, project scope, and equipment value.
Equipment Collateralization
The financed infrastructure becomes the primary collateral supporting the transaction.
Loan Documentation
Terms are structured around equipment performance, ownership profile, and risk assessment.
UCC Filing
The lender records a UCC-1 financing statement against the equipment.
Project Funding
Capital is deployed and project execution begins.
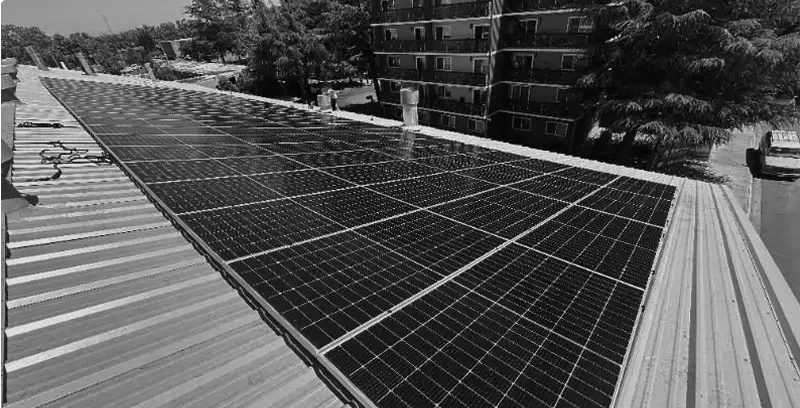
Capstone coordinates financing introductions through specialized commercial lending partners experienced in solar, roofing, HVAC, and energy infrastructure projects.
Commercial Solar & Energy Infrastructure
Structured financing solutions designed specifically for commercial energy projects.
Project-Specific Financing
Regional lenders often provide specialized solutions for qualified commercial ownership groups.
Institutional Structures
Financing solutions designed for larger ownership groups and multi-location operators.
UCC-1 refers to a financing statement filed under the Uniform Commercial Code that establishes a lender’s security interest in financed equipment.
A UCC-1 filing does not create a mortgage on the property. Instead, it establishes a lender’s security interest in specific equipment or assets, rather than the real estate itself.
Solar, roofing, and HVAC projects are all well-suited for UCC-1 financing, as this structure is designed specifically for equipment-based investments.
UCC-1 financing can play a role during refinancing. In some cases, the existing filing may need to be removed or subordinated to allow the new financing to move forward smoothly.
UCC-1 financing is commonly used by portfolio operators and can be structured to support multiple properties under a single financing strategy.
The financing structure influences refinancing flexibility, ownership strategy, transaction optionality, and long-term asset performance.